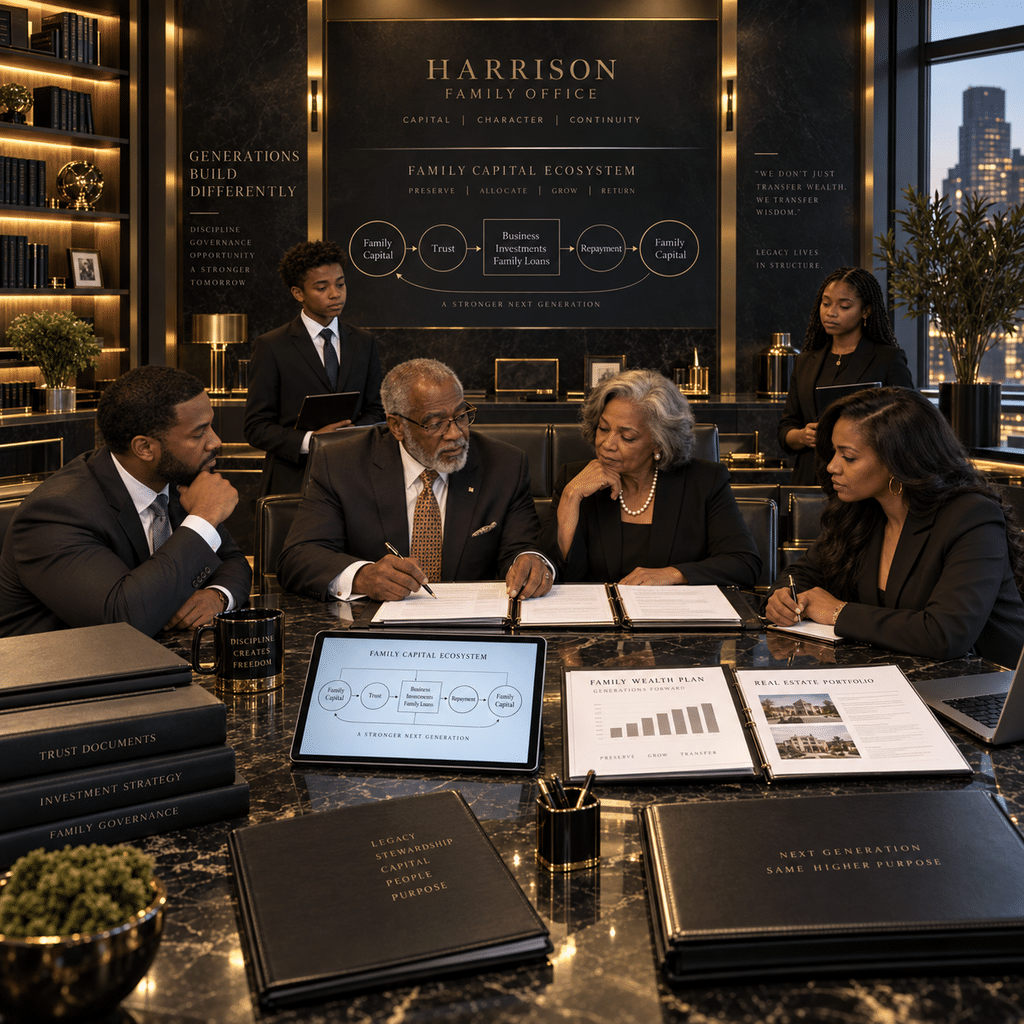
A Family Dynasty Internal Banking System
How families can move beyond one-time inheritance and create a disciplined capital system designed to finance homes, businesses, education, ownership, and opportunity across generations
Most families are taught to build wealth as individuals. Earn income, save money, purchase assets, prepare an estate plan, then leave whatever remains to the next generation.
A Family Dynasty Internal Banking System starts with a more sophisticated question:
Can a family build financial infrastructure capable of putting the same pool of capital to work repeatedly?
That question changes the entire architecture.
A family may combine carefully documented intrafamily lending, trusts, business ownership, insurance, accounting, professional administration, and written governance rules. Capital can finance one family member today, return through repayment, then finance another family member years later.
No commercial banking charter is created by calling the arrangement a “family bank.” The phrase describes a private family capital-management system, not an FDIC-insured institution. Its strength comes from disciplined structure rather than terminology.
Sharing the game means explaining the machinery. Wealth creation is only the first stage. Capital must also be governed, preserved, circulated, accounted for, and transferred intelligently.
1. The Architectural Shift: Moving From Inheritance to Financial Infrastructure
An inheritance transfers wealth. A family capital institution gives wealth rules, responsibilities, and a continuing economic purpose.
Traditional estate planning often concentrates on a single event: what happens when someone dies. Beneficiaries receive property, investment accounts, insurance proceeds, business interests, real estate, or cash. Once distributed outright, those assets become part of each beneficiary’s individual financial life.
That approach can be appropriate. It is not the only architecture available.
Families pursuing multigenerational capital can ask a different set of questions.
- Where should long-term family capital reside?
- Who decides when it can be used?
- Which purposes deserve financing?
- Should assistance arrive as a gift, a loan, an investment, or a trust distribution?
- What happens to the money after one family member receives it?
Consider $300,000 intended to help an adult child purchase a home. An outright gift transfers the economic value permanently. A properly structured family loan produces a different result. The family member obtains the home financing, but principal and interest can return over time to the lending family member or trust.
That distinction is fundamental. One method transfers wealth once. The other attempts to circulate capital.
Repeated circulation can matter enormously over several decades. Money used for one person’s home could later help finance another person’s company, education, real estate purchase, or other approved objective. The family begins thinking less like a collection of individual consumers and more like an institution responsible for a shared capital base.
Such a system should not be designed to keep descendants financially dependent. Its best purpose is the opposite. Access to family capital should carry expectations around preparation, repayment, accountability, stewardship, and productive use.
Key Takeaways:
- Inheritance and infrastructure solve different problems. One transfers property; the other establishes an ongoing financial process.
- Capital can be gifted, lent, invested, distributed, or retained. Each choice creates different economic and tax consequences.
- Recyclable capital can serve several generations. Repayment allows one pool of money to finance more than one person.
- Written rules reduce emotional decision-making. Family relationships should not substitute for financial standards.
Productive use should outrank casual access. Homes, enterprises, education, and carefully evaluated assets can receive different treatment from lifestyle consumption.
Education must accompany access. Family members should understand debt, interest, cash flow, ownership, and responsibility before receiving major capital.
Key Executive Tip: Before discussing trusts, insurance, or sophisticated entities, write a one-page statement explaining what family capital is supposed to accomplish. Structure should follow purpose. A family that cannot define the mission of its capital is not ready to design the institution controlling it.
2. The Three-Tiered Model: From Starter Bank to Multigenerational Institution
Families do not need identical structures. Capital size, complexity, objectives, and administrative capacity should determine the architecture.
Social media often presents dynasty planning as though every family needs an elaborate trust structure immediately. That can lead people to purchase complexity before they have enough capital or economic activity to justify it.
A better approach is progressive.
The original family-bank research used examples ranging from approximately $1 million to more than $25 million. Those figures can illustrate increasing institutional capacity, but they are not legal thresholds. Federal law does not declare that a family becomes a family bank at a specific net worth.
PrimalMogul’s educational model separates the concept into three levels.
| Level | Core Structure | Primary Objective |
|---|---|---|
| Tier I: Starter Family Bank | Family lending policy, direct loans, promissory notes, ledger, annual review | Establish disciplined family lending |
| Tier II: Structured Family Capital System | Trust planning, secured loans, business interests, professional tax oversight, insurance analysis | Coordinate several assets and borrowers |
| Tier III: Multigenerational Family Institution | Advanced trust planning, trustee governance, investment policy, business holdings, succession rules, insurance, tax coordination | Govern substantial family capital across generations |
Tier I: The Starter Family Bank
A starter system can begin with capital that the parents or other family members genuinely do not need for immediate living expenses, retirement security, emergency reserves, or near-term obligations.
Suppose $150,000 is available for long-term family lending.
Instead of making informal loans through text messages and verbal promises, the family adopts a written policy. Each borrower signs appropriate documentation. Payments move through traceable financial accounts. A ledger records principal, interest, payment dates, maturity, and remaining balances.
Institutional behavior begins before institutional wealth.
Tier II: The Structured Family Capital System
Complexity increases when several relatives need financing, a family company exists, significant real estate is involved, or trusts begin owning assets.
Informal decision-making becomes dangerous at this stage.
Loan approvals may require financial statements, collateral review, repayment analysis, business plans, documentation of purpose, concentration limits, and annual performance reviews.
Professional tax and legal oversight becomes increasingly valuable because one decision can affect several parts of the family balance sheet.
Tier III: The Multigenerational Family Institution
Large pools of family capital require governance that can survive the founders.
Trustees may administer assets according to formal governing instruments. Family enterprises may sit within a broader ownership architecture. Written investment policies may determine acceptable risk. Lending standards can define borrower qualifications. Succession provisions establish who assumes responsibility when the original decision-makers die or become incapacitated.
At this point, the family is managing more than wealth.
It is managing an institution.
Key Takeaways:
- Begin with the simplest architecture that performs the intended job.
- Small family lending systems can establish institutional habits before substantial wealth exists.
- More assets create more governance requirements, not simply more investment opportunities.
- Multiple borrowers require consistent underwriting standards.
- Business interests, trusts, real estate, and insurance introduce specialized legal and tax issues.
- Succession must address who controls the system, not only who benefits from it.
Key Executive Tip: Complexity should be earned. Do not spend $20,000 constructing an elaborate architecture for a family pool that can be responsibly governed with a simpler arrangement. Build the next layer when assets, risk, tax exposure, or administration create a genuine reason for it.
3. Mechanics of the Internal Capital Loop: Lending, Governance, and Repayment Discipline
The institution survives only when money returning to the pool receives as much attention as money leaving it.
A trust alone does not create an internal banking system.
Insurance alone does not create one.
A holding company does not create one either.
The defining mechanism is the capital loop.
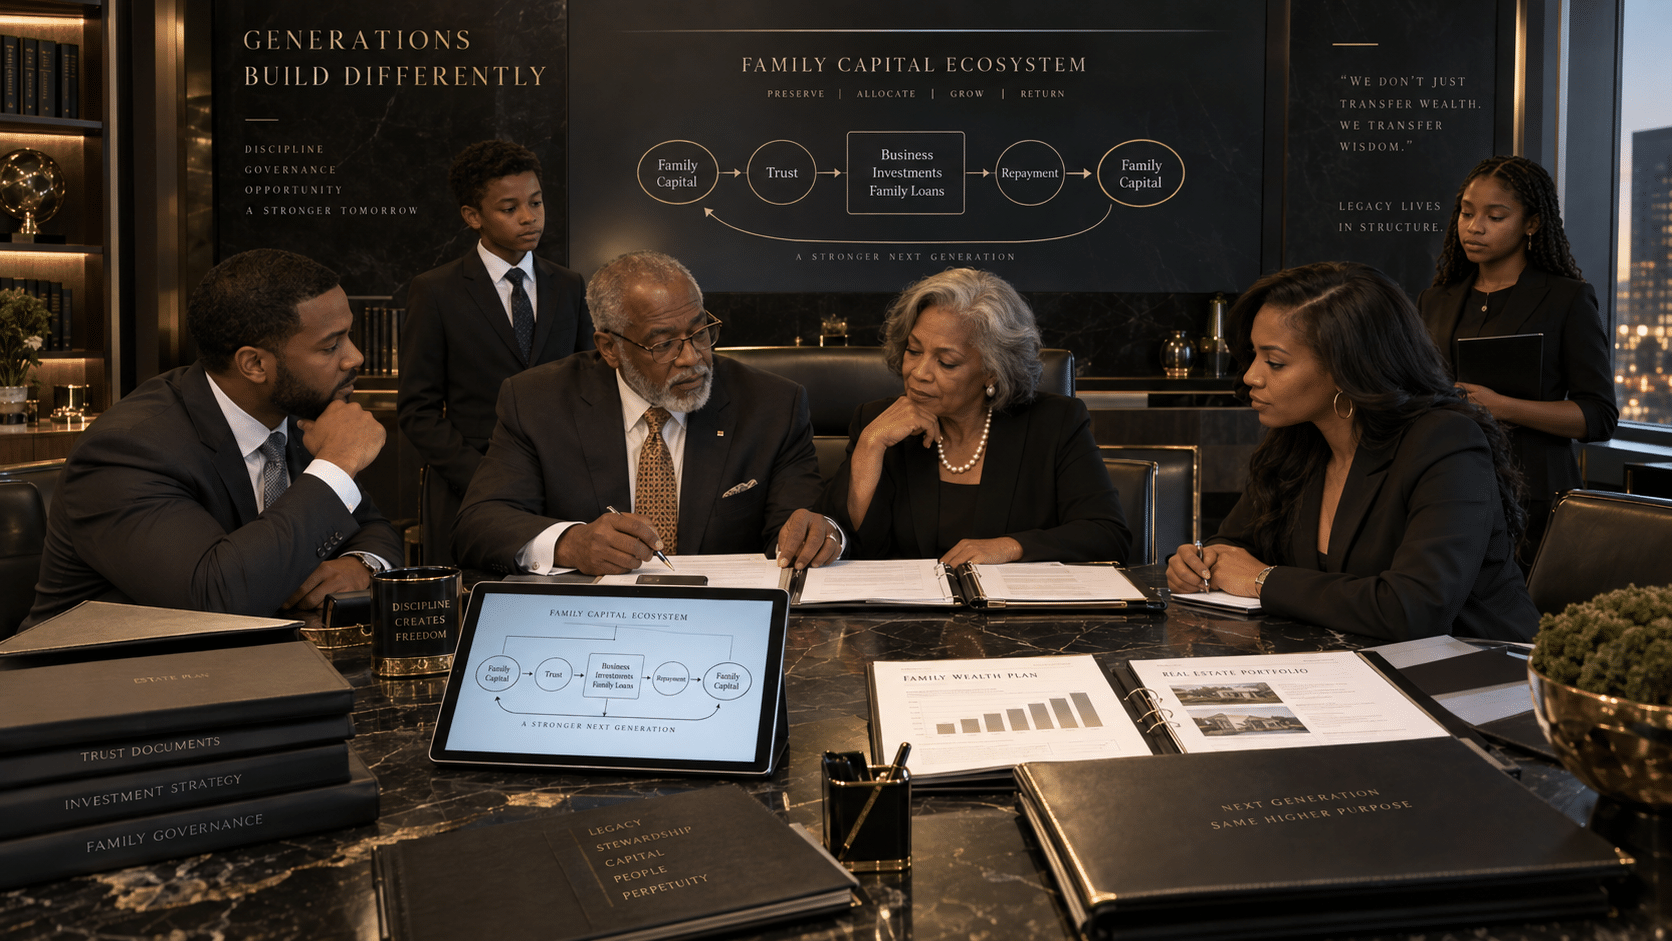
FAMILY CAPITAL POOL
        ↓
Approved Loan or Investment
        ↓
Home | Business | Education | Productive Asset
        ↓
Scheduled Repayment + Interest or Investment Return
        ↓
FAMILY CAPITAL POOL
        ↓
Capital Available for the Next Approved Use
Every serious lending system must answer two questions:
Who gets capital, and how does that capital return?
A borrower should generally receive formal loan documentation describing principal, interest rate, repayment frequency, maturity, default provisions, and collateral where appropriate.
Large real-estate transactions may require properly recorded security instruments. Business loans deserve serious underwriting because enthusiasm does not create repayment capacity.
Federal tax law also matters.
The IRS publishes Applicable Federal Rates, known as AFRs, each month. As of September 2026, annual-compounding AFRs are 4.18 percent for short-term obligations, 4.49 percent for mid-term obligations, and 5.12 percent for long-term obligations. Those figures change, so loan documents should use the appropriate rate and date rather than copying numbers from an old article.
Charging too little interest can produce below-market-loan consequences. Federal rules may treat forgone interest as though value moved between lender and borrower even when no cash interest was actually paid.
Families should therefore resist oversimplified online statements about “interest-free family loans.”
The system also needs underwriting.
Imagine three relatives requesting money from a $300,000 family pool. One wants $175,000 to purchase a profitable business. Another wants $150,000 toward a first home. A third wants $75,000 for personal spending.
Total demand exceeds available capital.
Someone must decide which request best fits the institution’s rules, risk tolerance, cash requirements, and purpose.
Written governance turns that difficult conversation into an economic decision rather than a popularity contest.
Key Takeaways:
- A promissory note should define the financial obligation.
- AFRs change monthly and should be checked when the transaction is created.
- Below-market loans can produce tax consequences even when relatives agree privately to different terms.
- Real repayment must occur on schedule if the system is intended to operate as lending.
- Collateral can reduce risk in appropriate transactions.
- A central ledger should track every outstanding obligation.
- Loan approval standards should exist before relatives ask for money.
Key Executive Tip: Treat repayment history as family financial intelligence. Over time, the ledger reveals who borrows responsibly, which uses of capital create economic value, where losses occur, and whether the family’s lending policy needs revision. The records become part of the institution’s decision system.
4. Integrating Business and Insurance: Capitalizing the System
Lending recycles existing wealth. Productive enterprises and properly designed insurance can potentially increase the capital available to future generations.
A long-duration family institution requires capital sources.
Savings may create the first pool. Repayments can replenish it. Investment returns may expand it. Business ownership can potentially generate additional value. Insurance can produce a major future liquidity event.
Businesses are particularly important because productive enterprises can create income beyond wages.
Imagine a family owns an operating company. Revenue pays expenses, employees, vendors, taxes, reserves, and reinvestment needs. Profits may eventually create distributions to owners.
Depending on entity structure, ownership rules, tax treatment, and trust design, some business interests may form part of a larger family ownership strategy.
Care is required. LLCs, partnerships, corporations, and S corporations follow different tax and ownership rules. Moving business interests into a trust without legal and tax planning can create unwanted consequences.
Insurance occupies a different role.
Life insurance death benefits are generally excluded from the beneficiary’s federal gross income, subject to important exceptions. Estate inclusion is a separate issue.
For certain families, an irrevocable life insurance trust, commonly called an ILIT, may own or receive insurance under carefully designed terms. After the insured dies, proceeds can potentially supply liquidity that the trustee administers according to the trust agreement.
Transferring an existing policy into an ILIT deserves special attention. Federal estate-tax rules include a three-year provision that can bring certain transferred life-insurance interests back into the decedent’s gross estate when death occurs within three years of transfer.
Policy selection also requires discipline.
Survivorship insurance may fit some estate-liquidity strategies because coverage generally pays after the second insured dies. Private placement life insurance belongs in a much more specialized category and requires sophisticated tax, securities, insurance, investment, and professional review.
No family should build its wealth strategy around whichever insurance product happens to be presented first.
Key Takeaways:
- Businesses can serve as productive capital engines when profits are governed intelligently.
- Family enterprise ownership should be coordinated with entity and trust rules.
- Life insurance can create liquidity, but income-tax and estate-tax treatment are separate questions.
- ILIT administration requires proper legal design and ongoing compliance.
- Transferring an existing policy can trigger the federal three-year estate rule.
- Survivorship policies and private placement structures serve very different markets and objectives.
- Insurance should support the family strategy rather than dictate it.
Key Executive Tip: Build the capital plan in the correct order: family objectives first, balance sheet second, trust and entity architecture third, insurance analysis fourth. Reversing that order often turns financial planning into product sales.
5. Implementation Logistics: Costs, Professional Teams, and Regulatory Realities
Sophisticated family finance requires administration. Legal documents without competent maintenance can become expensive decorations.
A family may spend substantial money establishing advanced trusts, but formation cost is only one part of the equation.
The source material reviewed for this curriculum cited illustrative legal drafting costs of approximately $5,000 to $20,000 or more for some dynasty trusts and roughly $3,000 to $6,000 or more for some life-insurance trusts. Professional trustee costs were illustrated at roughly 0.5 percent to 2 percent of assets annually, with additional accounting and administrative expenses.
Those figures should be treated as planning examples, not quoted market prices.
Actual fees vary significantly based on jurisdiction, assets, attorney experience, tax complexity, trustee duties, business holdings, real estate, number of beneficiaries, insurance arrangements, and administrative requirements.
Professional coordination matters more than shopping for the cheapest document package.
A strong starting team typically includes an estate-planning attorney, a CPA or tax adviser experienced with trusts and estates, and an insurance professional familiar with advanced estate planning. Larger systems may require investment counsel, business attorneys, valuation professionals, real-estate counsel, or corporate trustees.
Families should interview advisers as seriously as businesses interview senior executives.
Ask how many comparable cases they handled during the previous year. Request explanations in plain language. Determine who performs ongoing administration after documents are signed.
Regulatory boundaries also deserve respect.
Calling the structure a “family bank” does not create banking authority. The arrangement should not accept public deposits, represent itself as FDIC-insured, or operate as though ordinary trust documents create a licensed financial institution.
Trust jurisdiction deserves equal care. South Dakota receives attention in dynasty planning because state law states that the common-law rule against perpetuities is not in force there. That fact alone does not mean every family should establish a South Dakota trust.
Taxes, trustee location, governing law, family residence, administration, creditor law, fees, fiduciary standards, and the family’s actual objectives still matter.
Key Takeaways:
- Formation cost is only one component of long-term administration.
- Professional fees vary widely according to complexity and jurisdiction.
- An estate-planning attorney should usually lead the legal design.
- Tax professionals should evaluate lending, gifts, trust reporting, business ownership, and interest income.
- Insurance professionals should be evaluated on expertise, product analysis, and independence of judgment.
- Advanced systems may require professional trustees or additional specialists.
- The phrase “family bank” does not replace banking, securities, lending, tax, trust, or insurance law.
Key Executive Tip: Before signing anything, ask the professional team to draw the entire system on one page. Show ownership, trustees, beneficiaries, business interests, insurance, loan flows, tax reporting, and succession responsibility. If the architecture cannot be explained clearly on one page, the family should not fund it yet.
Mogul FAQ
The questions serious families should answer before creating an internal capital system
The following questions address the practical issues most likely to determine whether the concept becomes a durable institution or an expensive collection of documents.
1. Is a Family Dynasty Internal Banking System an actual bank?
No. “Family bank” is an informal description of private family capital management. It does not create a bank charter, FDIC insurance, or permission to accept deposits from the public.
2. Do we need $1 million before starting?
No federal law establishes a $1 million minimum. A family can begin with disciplined direct lending at considerably lower amounts. Advanced structures become more reasonable when the family’s capital, complexity, tax concerns, and long-term objectives justify the expense.
3. Can parents finance a child’s first home?
Potentially. The transaction may require a promissory note, appropriate interest, proper payment records, mortgage or deed-of-trust documentation, and tax review. State real-estate and lending laws also matter.
4. Can family members receive lower interest rates than they would receive from a commercial lender?
Potentially, but federal below-market-loan rules must be considered. AFRs provide an important federal reference point. Families should have a tax professional determine the correct treatment before setting loan terms.
5. What happens to the interest paid on a family loan?
Interest returns to the lender or lending trust rather than an outside financial institution, but it can represent taxable income. The economic benefit stays within the broader family structure while remaining subject to applicable tax rules.
6. Does every family need a dynasty trust?
No. A trust should solve an identifiable estate, ownership, governance, succession, tax, or asset-management problem. Some families can begin with simpler lending and estate-planning arrangements.
7. Is life insurance required?
No. Insurance is one possible liquidity and estate-planning instrument. Whether it belongs in the system depends on cash flow, age, health, objectives, policy economics, family needs, and professional analysis.
8. Can a trust guarantee protection from creditors or divorce?
No responsible adviser should make that blanket promise. Results depend on jurisdiction, trust design, timing, beneficiary rights, marital-property law, creditor type, and surrounding facts.
9. What destroys family internal banking systems most often?
Weak governance can be more dangerous than weak investment performance. Informal loans, favoritism, poor documentation, excessive distributions, missed payments, inadequate accounting, conflicts between relatives, and unprepared successors can break the recycling mechanism.
Power Conclusion
Wealth becomes more durable when a family stops treating money as a pile of assets and begins governing it as capital.
Building wealth and building a family financial institution are different achievements.
Income produces resources. Investments can increase those resources. Businesses can produce additional economic value. Insurance may provide future liquidity. Trusts can establish ownership and succession rules.
None of those elements alone creates a Family Dynasty Internal Banking System.
The institution begins when those pieces work under a coherent economic philosophy.
Capital receives a purpose. Borrowing follows standards. Loans are documented. Repayment is expected. Records preserve institutional knowledge. Professional advisers protect the architecture. Successors learn how the system works before they inherit responsibility for it.
The strongest principles are straightforward:
- Move beyond distribution and design for circulation.
- Keep productive capital capable of financing more than one generation.
- Place written governance above emotional decision-making.
- Treat repayment as preservation of future family opportunity.
- Teach descendants financial responsibility before transferring financial authority.
A family does not need to become extraordinarily wealthy before thinking this way. Institutional thinking can begin with the first disciplined loan.
Over time, the question changes from:
“What will we leave our children?”
to something far more consequential:
“What financial system will still be serving our family when we are no longer here to run it?”
Key Executive Tip: The highest form of family wealth planning is not transferring control forever to one generation. It is creating a system capable of producing responsible decision-makers in every generation.
Build the Financial Intelligence Behind the Family Institution
PrimalMogul AI helps serious entrepreneurs study ownership, capital, business structure, financial decision-making, and long-range family strategy before major decisions become expensive mistakes.
A Family Dynasty Internal Banking System crosses several disciplines at once. That is precisely why isolated advice can become dangerous. Business ownership affects estate planning. Lending affects taxation. Insurance affects liquidity. Trust design affects control. Family behavior affects everything.
A PrimalMogul AI membership gives you an organized environment for studying those decisions and preparing stronger questions before meeting licensed professionals.
- Use PrimalWealth AI to examine capital structure, financial organization, funding decisions, family lending concepts, and wealth-planning questions before professional review.
- Use the Mogul Vault to study ownership structures, business finance, estate-planning concepts, family enterprise strategy, and long-term asset management through structured educational resources.
- Use the BoardRoom Executive AI Council when a decision crosses finance, business ownership, technology, risk, leadership, and compliance at the same time.
Core Builds. Elite Expands. BoardRoom Commands.
Technical Documentation and Educational Disclaimer
Current federal figures and technical statements were reviewed against authoritative government sources for September 2026.
For September 2026, IRS Revenue Ruling 2026-17 lists annual-compounding AFRs of 4.18% short-term, 4.49% mid-term, and 5.12% long-term.
IRS guidance explains that below-market loans can create imputed-interest treatment and describes a limited exception for qualifying loans of $10,000 or less plus a separate net-investment-income limitation for certain gift loans totaling $100,000 or less. These provisions should not be interpreted as a universal exemption from properly structuring family loans.
For calendar year 2026, the federal annual gift-tax exclusion is $19,000 per individual recipient, while the basic federal estate and gift exclusion and GST exemption are $15 million.
The IRS states that life-insurance death benefits are generally excluded from a beneficiary’s gross income, subject to exceptions, while Form 706 instructions address transfers involving life-insurance policies within three years of death under Section 2035.
South Dakota law states that the common-law rule against perpetuities is not in force in the state. That provision does not, by itself, determine whether South Dakota is the appropriate trust jurisdiction for a particular family.
Educational disclaimer: This article provides general business and financial education. It is not individualized legal, tax, accounting, investment, securities, insurance, mortgage, or estate-planning advice. Trust creation, intrafamily loans, secured real-estate lending, insurance ownership, business transfers, gift planning, generation-skipping transfers, and asset-protection strategies can create substantial legal and tax consequences. Qualified attorneys, tax professionals, insurance professionals, and other licensed advisers should review the family’s specific facts before implementation.