
The Holding Company Blueprint: How to Own Multiple LLCs Without Putting Your Entire Business Empire at Risk
The Business You Built Could Become the Business That Exposes Everything You Own
PRIMALMOGUL AI | BUSINESS OWNERSHIP • HOLDING COMPANIES • LLC STRUCTURE • WEALTH BUILDING
Your first LLC starts making money. Customers are buying, business is improving, and you’re thinking about your next move.
Maybe you want to open another company, invest in real estate, purchase commercial trucks, launch an e-commerce brand, or build a second source of business income.
Suddenly, you’re operating several businesses, signing contracts, buying equipment, and taking on financial obligations. Everything looks successful from the outside.
But there’s one question most entrepreneurs overlook:
If one business gets sued, defaults on a loan, or suffers a serious financial loss, what happens to everything else you’ve built?
The answer depends on how your companies are legally organized, what they own, which obligations they share, and whether you’ve maintained genuine separation between them.
A holding company can help organize that ownership.
But here’s what most internet business influencers leave out: Forming multiple LLCs doesn’t automatically protect every asset, eliminate personal liability, or reduce your taxes.
You need to understand the structure before you spend money creating it.
That’s where this PrimalMogul AI blueprint begins.
1. What Is a Holding Company, and Why Would You Need One?
A holding company is a business entity established primarily to own interests in other companies or hold certain assets.
Rather than operating every business directly, the owner uses a parent company to hold ownership interests in separate businesses called subsidiaries.
The parent may be an LLC or corporation. The subsidiaries may also be LLCs or corporations, depending on their purpose and legal requirements.
Imagine you’ve built three businesses:
- A freight transportation company.
- An e-commerce clothing company.
- A commercial real estate business.
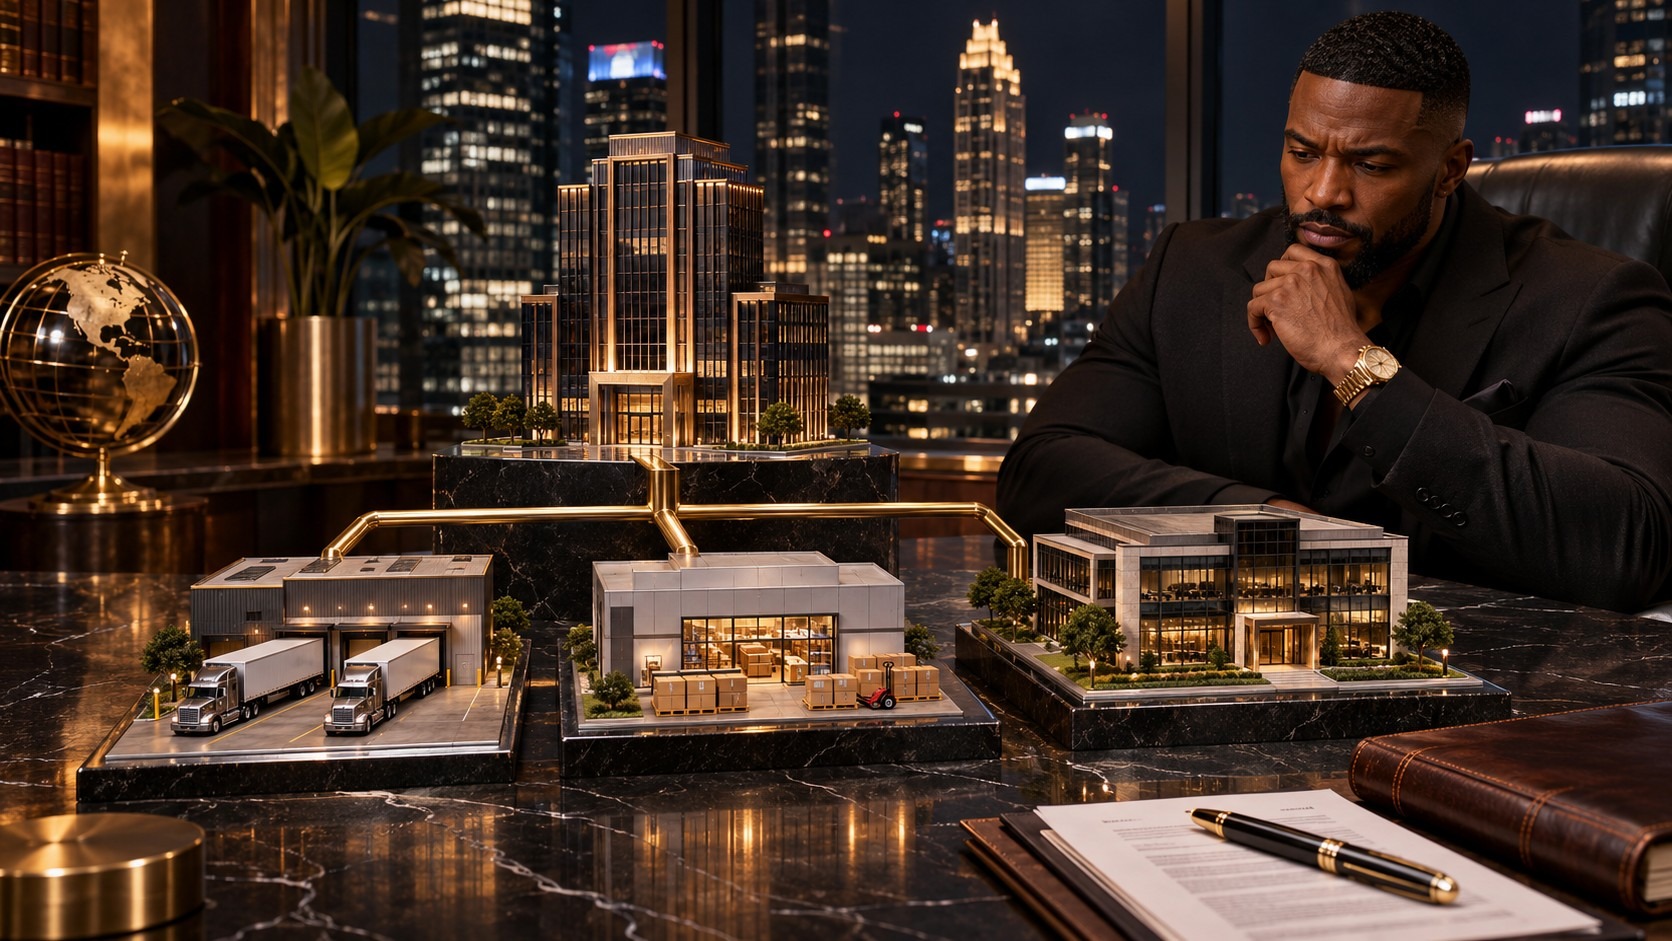
Instead of owning all three directly, you might create a parent company called Supreme Business Holdings LLC.
That parent owns the membership interests in three separate operating companies:
Supreme Business Holdings LLC: Parent Company
- Supreme Freight LLC — operates the trucking business.
- Supreme Commerce LLC — sells clothing and online products.
- Supreme Property LLC — owns or manages selected real estate assets.
These are hypothetical company names used to illustrate a possible structure.
The parent owns the subsidiaries, while each subsidiary conducts its assigned business activities.
The freight company signs transportation agreements. The e-commerce company handles retail transactions. The property company maintains its own property-related obligations.
This arrangement can create clearer ownership records and help distinguish one business’s risks from another’s.
The IRS recognizes that LLC members can include other LLCs, corporations, individuals, and other eligible owners. However, legal ownership and federal tax treatment are separate questions.
The objective isn’t to create as many companies as possible. The objective is to give each company a clear purpose.
Source: IRS: Limited Liability Company
2. The Real Advantage: Separate the Businesses Before One Problem Affects the Others
Picture an entrepreneur operating a trucking company and a profitable online retail business.
The trucking company carries commercial liability risks. Vehicles operate on public roads, drivers handle equipment, and transportation contracts introduce significant obligations.
The online retailer has different risks: product complaints, customer payments, vendors, intellectual property, and inventory.
Combining both activities inside one LLC may expose the same business entity’s assets to claims arising from either operation.
Separate operating companies can help establish legal boundaries.
If a trucking subsidiary faces a claim, creditors generally pursue assets and obligations legally attributable to that company. Assets owned by another properly maintained subsidiary aren’t automatically available simply because both businesses share a parent.
However, there are critical exceptions.
A parent might have guaranteed a subsidiary’s debt. Companies might be jointly responsible under a contract. Improper transfers, fraud, inadequate separation, or other legal circumstances could allow creditors to reach beyond the business where the problem began.
A holding company is not an invisible shield. It is a legal ownership arrangement whose effectiveness depends on the facts and applicable law.
Insurance remains essential. Proper contracts remain essential. Good financial records remain essential.
Creating a second LLC without changing how you operate may accomplish very little.
The strongest protection comes from matching the paperwork to the reality of the business.
3. The Seven Rules of Keeping Multiple LLCs Properly Organized
One of the biggest mistakes entrepreneurs make is creating several LLCs and then operating them like one informal business.
They use the same bank account, transfer money without documentation, sign contracts under the wrong company name, and forget which entity owns valuable equipment.
That’s where expensive problems begin.
Rule One: Give Every Company a Defined Responsibility
Document why each company exists.
Does it sell products? Own rental property? Provide consulting services? Operate trucks? Hold ownership interests in subsidiaries?
Every entity needs a legitimate business purpose.
Rule Two: Keep Financial Accounts Properly Separated
Businesses should maintain appropriately separate accounts and accounting records.
Money transferred between related companies should be documented as a lawful distribution, capital contribution, loan, payment, or another properly classified transaction.
Don’t treat company money as an unlimited personal checking account.
Rule Three: Sign Contracts Under the Correct Legal Entity
The company performing the work should generally be identified correctly in its agreements, subject to the approved legal structure.
If Supreme Freight LLC provides transportation services, its contracts should not casually identify Supreme Commerce LLC as the service provider.
Contracting mistakes can create disputes over responsibility.
Rule Four: Maintain Accurate Ownership Records
The holding company’s records should identify its interests in each subsidiary.
Operating agreements, membership ledgers, ownership approvals, and required state filings must accurately reflect the arrangement.
Rule Five: Insure Each Business for Its Actual Risks
An LLC alone does not pay legal defense costs or cover uninsured losses.
A transportation company, professional-services business, and property owner may need substantially different insurance.
Rule Six: Document Transactions Between Related Companies
When companies share equipment, employees, property, management services, or loans, those arrangements may require written agreements and defensible accounting treatment.
The transfers must reflect real economic activity rather than being invented to manufacture deductions.
Rule Seven: Keep Every Company in Good Standing
Pay required taxes, complete state filings, maintain applicable licenses, and preserve records.
For example, California LLCs generally file a Statement of Information within 90 days of registration and every two years afterward.
The central lesson is simple:
Separate companies must be treated as real companies: not different names for the same undocumented activity.
4. The Tax Question: Does a Holding Company Actually Save Money?
This is where entrepreneurs need to be particularly careful.
Social media frequently presents holding companies as secret tax-saving structures available to anyone who files the right paperwork.
That claim is misleading.
Creating a holding company does not automatically lower federal income taxes.
An LLC is a legal structure established under state law. Its federal tax classification depends on ownership and valid elections.
A single-member LLC may be disregarded as separate from its owner for federal income tax purposes. An LLC with multiple members is generally taxed as a partnership unless it elects another available classification.
Some LLCs elect corporate tax treatment.
The structure matters because a wholly owned subsidiary may remain legally separate under state law while its income is reported through its owner for federal income tax purposes.
That does not mean the subsidiary can ignore payroll, employment taxes, applicable state taxes, or other legal responsibilities.
Source: IRS: Single-Member LLCs
What about S corporations?
An entrepreneur might already operate an LLC taxed as an S corporation and want to place it beneath another LLC.
That restructuring requires particular attention.
S corporations face strict shareholder eligibility rules. Partnerships and corporations generally cannot be S corporation shareholders, although certain qualifying arrangements involving eligible owners, trusts, and disregarded entities may be permitted.
Placing an S corporation beneath an improperly classified holding company can create serious tax problems.
The correct structure must be reviewed before ownership changes take effect.
Where legitimate tax planning enters
Tax planning may involve reasonable business deductions, compensation, distributions, asset ownership, depreciation, and selecting appropriate tax classifications.
Those decisions require examining the entire company’s situation.
A profitable business may benefit from one arrangement while another company with different owners, revenue, employees, or plans may be better served by something else.
The real goal is to pay the taxes legally owed without creating unnecessary costs or risks.
5. The Cost Nobody Mentions: Multiple LLCs Can Become Expensive
Before forming three or four companies, calculate what maintaining them will cost every year.
A business entity may require state taxes, annual or periodic reports, registered-agent services, bookkeeping, tax preparation, insurance, and legal assistance.
These expenses don’t disappear because a subsidiary has little revenue.
Let’s examine California.
The California Franchise Tax Board generally requires LLCs organized or doing business in California to pay an $800 annual LLC tax, with applicable exceptions.
Certain LLCs also owe an additional fee when their California total income reaches specified thresholds.
Source: California Franchise Tax Board
Consider a hypothetical entrepreneur with three California LLCs.
At $800 each, that creates $2,400 in annual LLC tax alone, assuming all three are subject to the tax.
That figure excludes other filing requirements, professional fees, insurance, and business administration.
Now imagine each company also requires separate accounting work.
The cost of ownership becomes considerably higher.
For an entrepreneur generating modest revenue from one primary business, that complexity may be unnecessary.
For an owner managing several valuable properties or substantially different business activities, the additional expense may be justified.
A company structure should protect and support the business—not consume money simply to look sophisticated.
Ask whether each new entity solves a real ownership, contractual, financing, or risk-management problem.
If you cannot identify that purpose, reconsider whether another company is necessary.
6. Building Business Credit and Preparing Multiple Companies for Financing
A holding company can make an ownership structure look organized.
But lenders do not approve financing simply because someone presents an impressive corporate chart.
Banks want to understand the business receiving the money.
They may examine revenue, operating history, cash flow, credit, collateral, debt obligations, company ownership, and the intended use of funds.
If Supreme Freight LLC applies for equipment financing, the lender may investigate that company’s operations and financial obligations.
The lender may also review the holding company, related businesses, beneficial ownership, and any proposed guarantors.
A parent company does not automatically transfer the creditworthiness of one subsidiary to another.
Nor does using several LLCs automatically eliminate personal guarantees.
Certain SBA loans and other commercial financing arrangements may require qualifying owners to personally guarantee repayment.
For that reason, business owners need accurate records showing where revenue is earned, who owns the assets, what debts exist, and how related companies interact.
The Funding-Readiness Advantage
At PrimalMogul AI, we encourage entrepreneurs to prepare before requesting money.
Our 70-question Funding Roadmap helps members examine important readiness factors and identify issues that may deserve attention before approaching a lender.
That preparation might reveal incomplete company records, insufficient operating history, cash-flow problems, or questions about business ownership.
None of those problems is solved merely by forming another LLC.
Funding preparation starts with understanding what the lender will evaluate.
Build a company that can explain its financial position—not one that relies on its name or legal structure to impress the bank.
7. How to Move From One LLC to a Holding Company Without Creating a Mess
Suppose you already own one successful business.
Your next move is launching another company.
Do you automatically create a holding company?
Not necessarily.
First, evaluate the existing business and your reasons for expanding.
Consider whether you will own the second company personally, through a parent LLC, or through another approved ownership arrangement.
The decision depends on legal liability, taxes, investors, financing contracts, licensing, and long-term plans.
Start with an ownership review
Identify every existing company, its owners, significant assets, debts, contracts, and tax classification.
If you plan to transfer an existing LLC into a holding company, have qualified professionals assess the transfer.
Ownership changes may require operating agreement amendments, lender consent, licensing reviews, tax analysis, or other documentation.
Decide what the holding company should actually own
The parent might own membership interests in operating subsidiaries.
Some business structures also involve separate entities owning commercial property or selected assets.
Those arrangements introduce their own tax, insurance, financing, and contractual considerations.
Don’t move valuable assets simply because someone online recommends it.
Prepare for ongoing management
Develop reliable procedures for company records, tax deadlines, financial reporting, and authorized transfers.
Keep track of the companies’ separate financial positions.
A serious ownership structure requires serious administration.
The strongest business owners don’t collect LLCs. They build companies with clear responsibilities and financial discipline.
Key Executive Outro: Ownership Is More Than Putting Your Name on a Company
Starting an LLC is relatively straightforward.
Operating several companies responsibly is a different responsibility.
You must understand which business owns the assets, who signs the contracts, where money enters, which obligations are guaranteed, and how the companies are taxed.
That’s the difference between collecting business registrations and building an organized ownership structure.
A holding company can be useful when your operations, investments, or expansion plans justify it.
But your first obligation is to understand the company you already own.
Build the right structure for your actual business: not for the image of success.
How PrimalMogul AI Helps You Prepare for Smarter Company Ownership
You do not need to become a tax attorney or corporate accountant to make better business decisions.
You do need enough knowledge to understand the questions, compare options, and recognize when professional assistance is necessary.
PrimalMogul AI is a private AI-powered business and leadership intelligence platform engineered to help entrepreneurs build profitable businesses.
Our BoardRoom membership brings together specialized advisors, practical resources, and company intelligence to help you examine important decisions before acting.
LLC Launch Guide: Learn about business formation, ownership structures, documentation, and questions to address before registering another entity.
Chairman AI and the Executive Council: Examine the risks, financial consequences, and strategic reasons behind an expansion or restructuring decision.
Company Memory: Keep important company facts, goals, and ownership information organized for use by your authorized executive advisors.
CFO AI: Examine operating expenses, capital needs, financial assumptions, and the costs of managing multiple businesses.
Mogul Vault: Explore business education, ownership guides, checklists, and other practical resources.
Our standard remains:
Business Intelligence Before Execution.
We help you understand and prepare. Your attorney, CPA, lender, and other qualified professionals handle matters requiring their licenses or independent professional judgment.
Mogul FAQ: Seven Questions Every Business Owner Should Ask
1. Can one holding company legally own several LLCs?
Yes. LLCs generally may own interests in other LLCs. The arrangement must comply with applicable state law, operating agreements, and other ownership restrictions.
2. Does forming a holding company protect my personal assets?
Not automatically. Liability protection depends on the structure, business conduct, applicable law, contracts, and guarantees. Personal guarantees and misconduct can create exposure beyond an LLC.
3. Should I put all my businesses under one LLC?
That depends on the activities and risks involved. Businesses with different contracts, assets, liabilities, and ownership arrangements may benefit from separate entities. Additional companies also create costs.
4. Does each subsidiary need its own bank account?
Separate accounts and records are generally advisable for distinct legal entities. Federal EIN requirements vary according to tax classification, employment, and other circumstances, so an LLC does not always need a separate EIN merely because it exists.
5. Will a holding company reduce my taxes?
Not simply by existing. Federal and state tax treatment depends on classification, ownership, transactions, and elections. Review the proposed structure with a qualified tax professional.
6. Can I transfer my existing LLC into a new holding company?
Often, ownership interests can be transferred or reorganized, but the process may trigger consent requirements, financing restrictions, tax consequences, or documentation changes. Have the arrangement reviewed before making transfers.
7. When should I consider creating a holding company?
Consider one when you’re planning multiple operating businesses, acquiring valuable assets, bringing in investors, or organizing long-term ownership. The strongest time to evaluate it is before signing major contracts or making costly ownership changes.
Power Conclusion: Build the Company Behind the Company
Your business should become more organized as it grows, not more dangerous to manage.
The next LLC you form should have a reason to exist. Every ownership decision should be understood. Every major asset deserves appropriate legal and insurance planning.
Wealth-building starts with earning money, but lasting business ownership also requires controlling expenses, understanding risks, and making intelligent decisions about what you own.
Don’t build five companies you don’t understand. Build a business structure you can explain, manage, and grow.
PrimalMogul AI helps serious entrepreneurs examine those decisions with specialized business intelligence, practical education, and executive-level decision support.
Your Next Move
Join PrimalMogul AI BoardRoom and gain access to:
- Your six-seat Executive Council to examine major business decisions.
- Company Memory and financial tools to organize important business information.
- LLC education and funding-readiness resources to help prepare for formation and financing discussions.
- The Mogul Vault and specialized AI advisors to keep building your business knowledge.
Explore the PrimalMogul AI BoardRoom Membership
Step inside. Build with power. Lead with intelligence. Move like a mogul.
Professional disclosure: This article provides general business education and does not constitute individualized legal, tax, accounting, lending, or investment advice. Entity formation, restructuring, asset transfers, liability protection, and tax elections require analysis of the specific facts and applicable law. Consult qualified professionals before acting.